A Michigan couple’s $9,000 bill shows how pregnancy costs can exceed insurer estimates. Five steps can help families budget and avoid coverage gaps.
Grace and Daniel Griffin expected pregnancy to strain their budget. They tried to plan before conceiving, using their health plan’s estimate for a routine pregnancy and delivery: about $2,700 in out-of-pocket costs. By early October, after their daughter’s June birth, Grace says their expenses had passed $9,000.
The gap points to a difficult problem for families trying to plan care: a broad estimate may not reflect what a particular patient will owe as tests, visits, and delivery charges accumulate. The Griffins’ experience also shows why it helps to understand a plan’s cost-sharing rules before bills arrive, and to check coverage details throughout pregnancy.
“This whole experience has me wondering (keeping me up at night, actually): Can we ever afford to have another child?”
— Grace Griffin, Calumet, Michigan
Both 26, the Griffins began setting money aside before they tried to have a baby. Grace first found a cost estimator linked to her UnitedHealthcare student plan, but it required billing codes for the procedures she might receive. She didn’t have those codes. A search through the insurer’s website led her to its Summary of Benefits and Coverage information, which gave the $2,700 estimate.
“We thought, ‘OK, that’s doable,’” she said. “We should be able to save up that much and pay for that out-of-pocket.”
Then the bills started to accumulate. Grace met her $500 deductible early in the pregnancy. Her plan also charged 20% coinsurance for in-network care, leaving her responsible for a share of covered service costs after the deductible. Routine tests, including blood work to check iron levels and screen for gestational diabetes, cost a couple of hundred dollars per visit, she said.
The hospital later reported about $18,000 in charges for the delivery. The Griffins’ explanation of benefits showed that they would owe a substantial portion. “I thought, ‘Oh no, it’s going to be a lot,’” Grace said. “Much more than we budgeted for.”
Why estimates can fall short
Patients still lack the individualized advance cost estimates that federal lawmakers intended insurers to provide. The 2020 No Surprises Act included a requirement for an “advanced explanation of benefits” estimating a patient’s share of scheduled care. The requirement was due to take effect Jan. 1, 2022, but federal regulators have not implemented it, despite pressure from members of Congress.
Sabrina Corlette, a research professor and co-director of Georgetown University’s Center on Health Insurance Reforms, says the delay has left people without information they have a legal right to receive. “So, it’s basically 4½ years since this was supposed to be available, and I think it’s a source of a lot of frustration for a lot of folks,” she said. “People have a right under the law to know these things.”
Billing practices may also change. Starting Jan. 1, long-standing maternity codes that group much of pregnancy care are due to be replaced with more detailed codes for prenatal care, labor, delivery, and postpartum care. The shift could make the prices of individual services more visible. Corlette is less certain that it will help patients budget: “I could see where it might be advantageous to the provider,” she said. “But I’m not sure I’m seeing benefits to the patient.”
Five steps to prepare for pregnancy expenses
1. Enroll your baby within your plan’s deadline.
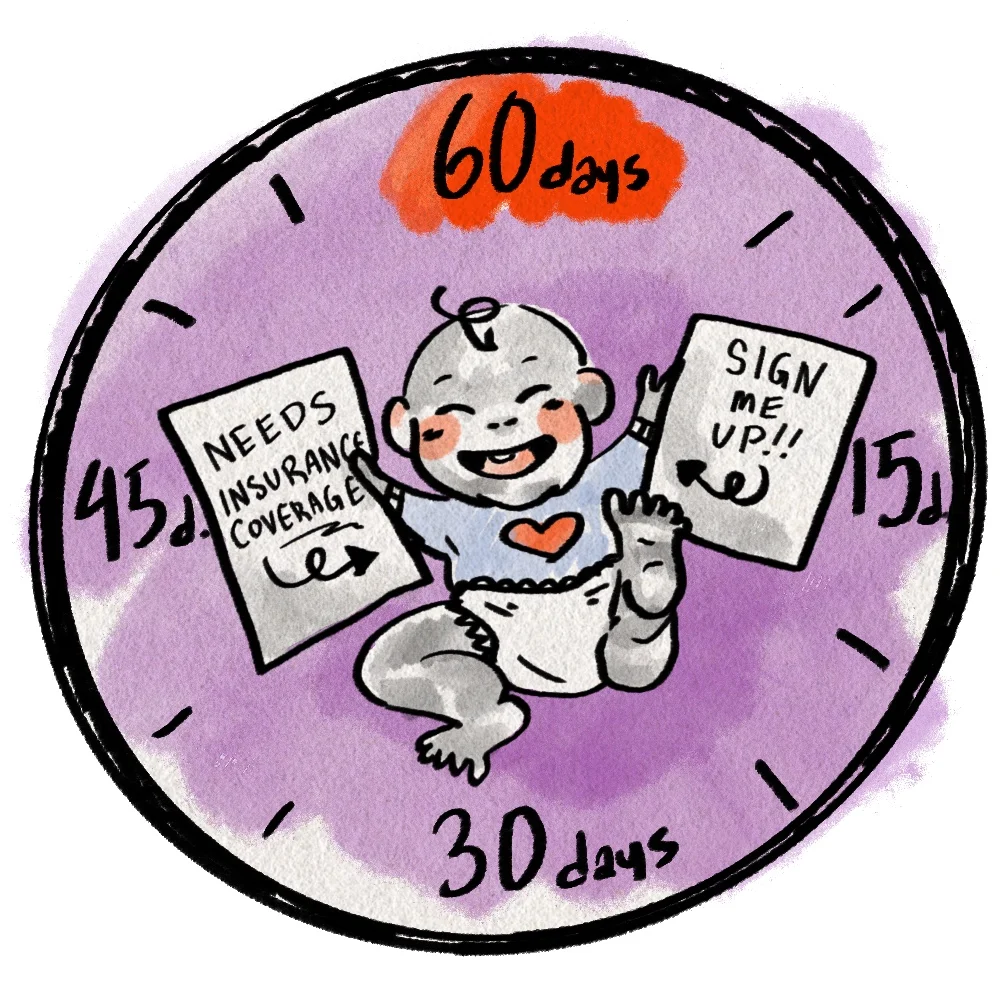
A birth generally creates a special enrollment period, allowing parents to add a newborn outside the annual open enrollment window. The deadline depends on the plan: many employer plans allow 30 days, while Marketplace plans generally allow 60. Missing the cutoff can leave a baby without coverage until a later enrollment period.
Michelle Critzer, a sales representative in Ventura, California, missed the deadline for her second son, Hudson, who was born in February 2026. She has asked her insurer to make an exception, so far without success. “The way they set hard must-dos within 30 days of having a baby is actually insanity,” she said.
Hudson was enrolled through his father’s workplace plan, which gave the family a 60-day window. Critzer says that coverage is not as strong as her own insurance, but it means her newborn is insured while she continues seeking enrollment in her plan.
2. Find your deductible, coinsurance, and out-of-pocket maximum.
The deductible is what you pay before your plan begins covering many costs. Copayments are fixed charges for particular services. Coinsurance is a percentage of a service’s cost, so the amount can vary from one bill to another.
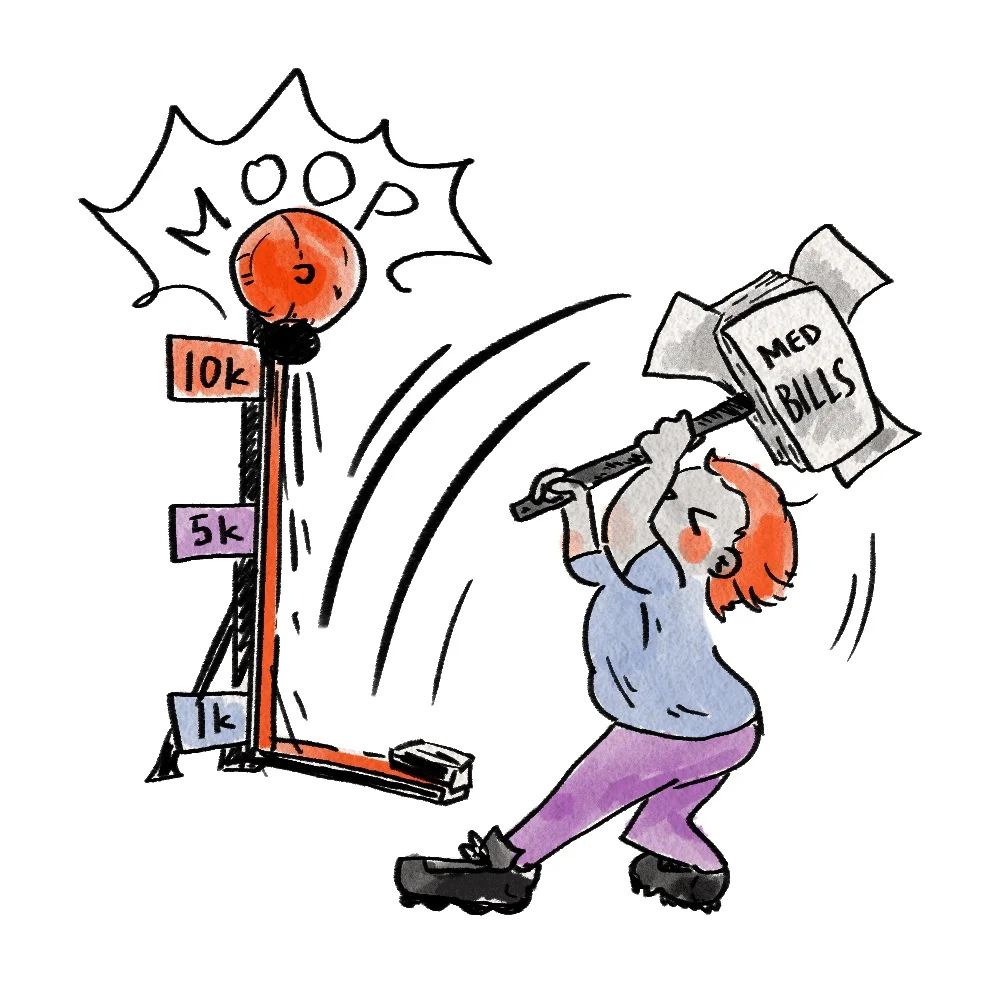
Ask your insurer for your maximum out-of-pocket amount, often shortened to MOOP. It sets a ceiling for what you pay in a year for covered, in-network care. In 2026, the Affordable Care Act’s limit is $10,600 for an individual and $21,200 for a family. Plans can set lower limits. Once you reach your plan’s cap, insurance pays the full cost of covered in-network care for the rest of that year.
That figure can help with planning, but timing matters. If pregnancy spans two plan years, the out-of-pocket maximum resets at the start of the second year. A patient could therefore face substantial expenses in both years. Some plans also track separate in-network and out-of-network maximums; the out-of-network limit may be twice as high, and costs may not count toward the in-network cap.
The Griffins’ family maximum was $18,000, while Grace’s individual maximum was $9,000.
3. Check the network for every part of your care.
An in-network obstetrician doesn’t guarantee that the hospital, laboratory, or imaging center involved in your care is also in-network. Ask your doctor’s office where it sends tests and explicitly request an in-network provider when possible, Corlette advised.
Federal law protects patients from certain surprise bills when they receive care at an in-network hospital or other in-network facility from an out-of-network provider. Still, checking the network ahead of time can help you understand which charges will count toward your plan’s in-network limit.
4. Review bills and challenge denied charges.
Some recommended prenatal services are covered without additional cost under the Affordable Care Act. They include prenatal visits, folic acid, anxiety and depression screening, and breastfeeding and lactation counseling and supplies. Yet patients can still receive bills for services that should have been covered.
Learn which pregnancy-related services your plan must cover, then compare bills with your explanation of benefits. If an insurer refuses to pay for a covered charge, consider filing an appeal. Catching a billing problem early may give you a clearer path to correcting it.
5. Ask about financial help before bills become overdue.
Hospitals often have financial assistance programs that can reduce bills or arrange payments. Ask your hospital and other providers what help they offer. Corlette recommends getting any payment arrangement formally agreed upon in advance, so there’s less chance the account will be sent to collections unexpectedly.
Families can also look for local assistance. Grace qualified for Michigan’s Rx Kids program, which provides eligible families in certain communities with $1,500 during pregnancy and $500 per month for the baby’s first six months or year of life. The payments helped keep medical bills from consuming the Griffins’ emergency savings. “It takes a lot of pressure off,” she said.
For families weighing the cost of pregnancy, the practical starting point is to treat an insurer’s estimate as one input, then learn the plan’s limits, verify provider networks, and keep checking bills as care unfolds. Those steps can’t make every expense predictable, but they can make the financial exposure easier to see before it arrives.
Healthcare Helpline helps you navigate the health system hurdles between you and good care. Send us your tricky question and we may tap a policy sleuth to puzzle it out. Share your story. The crowdsourced project is a joint production of NPR and KFF Health News.
KFF Health News is a national newsroom that produces in-depth journalism about health issues and is one of the core operating programs at KFF—an independent source of health policy research, polling, and journalism. Learn more about KFF.
This article first appeared on KFF Health News and is republished here under a Creative Commons Attribution-NonCommercial-NoDerivatives 4.0 International License.
Discussion
Sign in to join the discussion.